1 MIN READ·Oct 20, 2026·Written by Bhavishya Bhardwaj
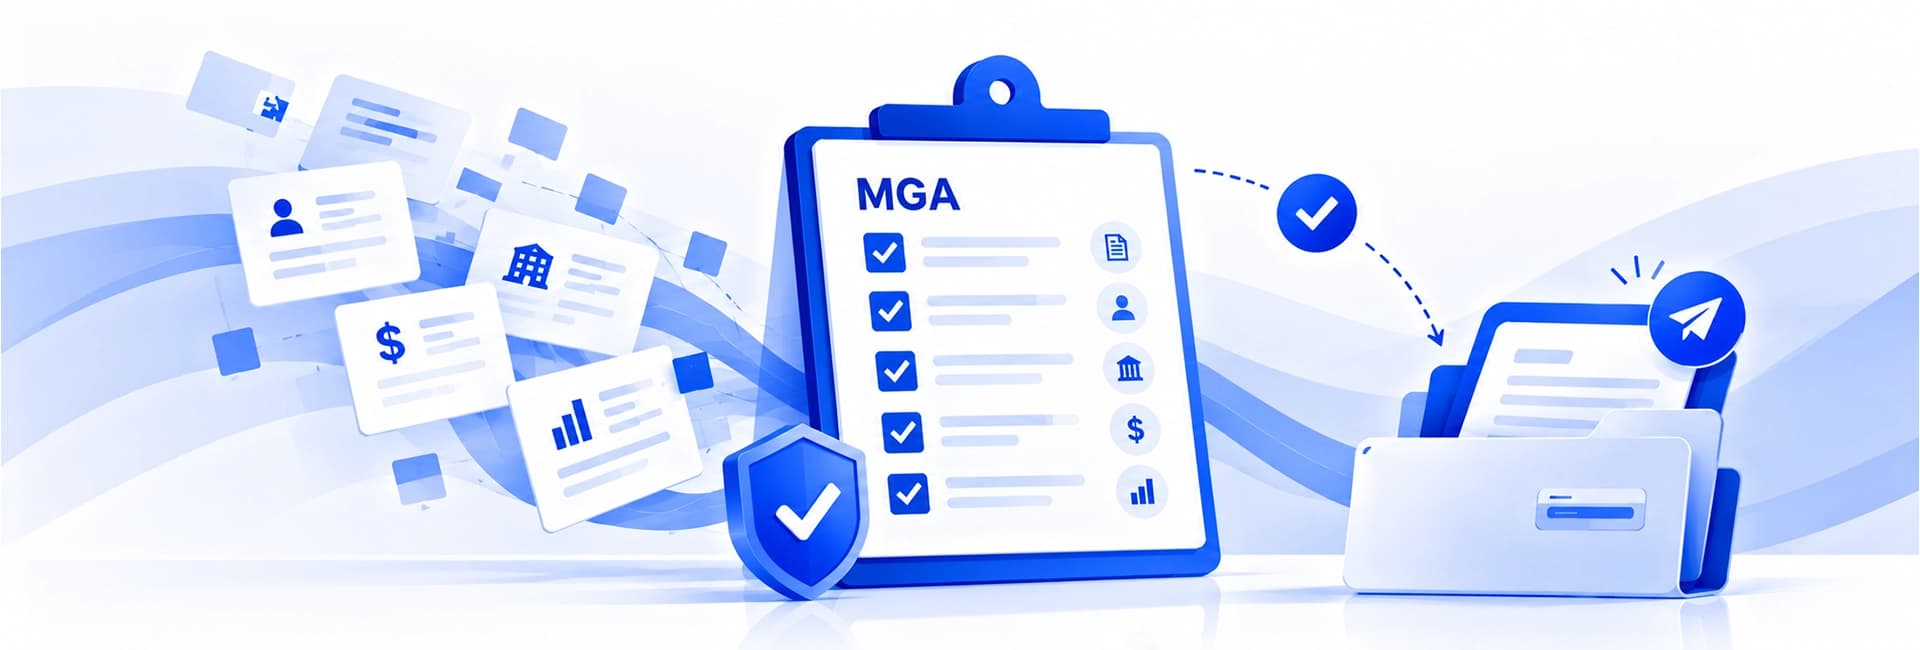
A submission can look complete and still not fully prepared for underwriting.
The application is there. The loss runs are attached. The exposure schedule has been included. But once underwriting starts reviewing the file, small issues begin to surface. A value does not match. A document is outdated. A required field is missing. The coverage request is not completely clear.
That is where submission readiness starts becoming a data quality problem.
For MGAs, the challenge is not just gathering the essential documents, but also making sure the information is accurate, consistent, current, and useful enough for underwriting.
A step-by-step data quality checklist can help teams catch those issues earlier, reduce avoidable follow-ups, and improve the overall quality of submission processing before the file moves forward.
For an MGA, submission readiness means the file is not only complete but usable for underwriting.
The information should be complete, current, consistent across documents, and clear enough for an underwriter to begin evaluating the risk without first having to reconstruct the account. That distinction matters.
A submission may contain applications, schedules, loss runs, and supporting documents and still not be ready if figures conflict or important information is missing. FBSPL treats readiness as a combination of data completeness, eligibility validation, risk verification, supporting documentation, and connected processing.
Poor-quality submission data rarely creates just one problem.
A missing exposure value leads to a follow-up. Conflicting totals require another review. An outdated loss run sends the file back for clarification. What should have moved into risk assessment remains stuck in preparation.
For MGA teams, better data quality can reduce that friction before underwriting begins. It can also protect underwriting capacity. The less time underwriters spend finding, comparing, and correcting basic submission information, the more attention they can give to risk selection, pricing, and broker relationships.
This is why submission quality control belongs upstream, not at the point when an underwriter is already trying to evaluate the account.
There is no single submission checklist that applies to every MGA, carrier, class, or program. Requirements differ depending on the risk and intended market.
The quality checks behind a strong submission, however, are fairly consistent.
Start with the information that identifies the account.
Check the named insured, business details, locations, broker information, proposed effective date, and other relevant identifiers. Then compare them across the submission.
An entity's name written one way on the application and another way on a schedule may look harmless, but inconsistencies become challenging to resolve once information has moved through multiple systems.
The first question should be simple: Does every document refer to the same account in the same way?
Underwriting should not have to guess what is being requested.
The submission should make the coverage, limits, deductibles, effective dates, and relevant program or class clear. Eligibility criteria should also be checked before the account progresses. FBSPL identifies consistent appetite and eligibility validation as one of the areas that influence submission readiness.
Exposure information can appear in applications, spreadsheets, schedules, prior policies, supplemental forms, and other records. The numbers should tell the same story.
Depending on the line of business, teams may need to compare:
For Example - A property application lists $12 million in total insured value, while the attached location schedule totals $13.4 million. Every requested document may technically be present.
But which figure should the underwriter use?
Until the difference is understood, the submission is not truly ready. That is the type of discrepancy a good data quality checklist should catch before underwriting has to.
Having a document attached is not the same as having a usable document. Check whether relevant forms and supporting records are complete, readable, associated with the correct account, and dated or signed where required.
The specific records needed will vary by risk. Property, commercial auto, workers’ compensation, professional liability, and other classes will require different supporting information, so the review process will vary accordingly.
Do not stop at “loss runs received.”
Check whether the loss information relates to the right entity and relevant policy period. Review open claims, severe or unusual losses, and anything that may require additional context.
If historical information is unavailable, that should be clearly identified rather than left for the underwriter to discover. Usable loss information tells underwriting what happened and provides enough context to understand material loss activity.
Some of the biggest submission delays come from very ordinary issues.
Look for blank fields, duplicate attachments, expired records, unreadable files, contradictory values, incorrect dates, and inconsistent insured information. Insurance experts recommend removing duplicate, blank, expired, unreadable, or unrelated files and calling out missing information, ownership, and expected follow-up.
If something cannot be resolved immediately, flag it clearly. An identified exception is easier to manage than one buried inside the file.
Before moving the account forward, stop looking at individual documents and look at the submission as a whole.
Ask: Does this file tell one consistent risk story?
Key values should agree. The coverage request should be understandable. Material gaps should be visible. Outstanding follow-ups should have an owner. Always remember that the purpose of final submission quality control is not to make underwriting decisions in advance. It is to make sure the underwriter receives a file that is ready for those decisions.
Better submission readiness improves more than intake quality. It helps MGAs reduce rework, protect underwriting time, and keep submission processing moving.
For MGAs operating at higher volumes, that distinction can make submission capacity easier to manage.
A checklist should create discipline without assuming every risk, program, or submission will follow the same requirements. A few considerations matter when building one:
A property program and a professional liability program will not require the same data, documents, or eligibility information.
Teams should distinguish between missing information that prevents a submission from moving forward and items that can reasonably remain open for later follow-up.
When data or documentation is incomplete, responsibility for obtaining and updating that information should be clearly defined.
Information should be checked across applications, schedules, spreadsheets, loss runs, and other supporting documents rather than relying on a single source.
Extraction and workflow tools can support data checks, but conflicting, incomplete, or ambiguous information may still require human review before the submission moves forward.
The most effective checklist is not necessarily the longest. It is the one that reflects how the MGA evaluates risk, handles exceptions, and moves submissions through the process.
If the answer to any of these questions is no, your submission is complete, but not underwriting-ready. You need to work on its data-readiness.
Better quality starts by defining what “ready” means before files begin moving through the workflow.
Keep in mind that if exposure schedules from one source frequently need correction, or a particular field is repeatedly left incomplete, that pattern is a useful operational data that should not be ignored. Undoubtedly, technology can assist with extraction, validation, routing, and visibility. But the bigger opportunity lies in creating a process where quality problems are found closer to intake instead of being passed downstream.
For MGAs managing higher submission volumes, maintaining consistent intake and administrative support can become a capacity issue of its own.
FBSPL supports P&C insurance operations across new business activities including data collection, AMS activities, ACORD forms, and carrier submissions. Our P&C service capabilities also include carrier portal activities, AMS updates, and workflow tracking.
Our experts help MGAs with organizing submission information, maintaining system records, preparing ACORD-related information, supporting carrier submissions, and managing administrative follow-ups.
We keep your routine work moving accurately so internal underwriting and operations teams do not spend unnecessary time correcting avoidable data and documentation issues.
Submission quality becomes harder to manage when volume grows faster than the process behind it.
If underwriters regularly chase missing information, intake teams keep reconciling the same types of discrepancies, or accounts spend too long between receipt and actual underwriting review, adding another checklist alone will not solve the issue.
The bigger goal is to move cleaner, more reliable information toward underwriting from the beginning.
A data quality checklist helps insurance teams verify whether submission information is accurate, complete, current, and consistent before underwriting. It can cover account information, exposure data, coverage requests, loss history, supporting documents, discrepancies, and final quality control.
Get the latest insights on insurance operations, policy management, and industry best practices.